 Horus
How many investors should you pitch for a seed round
Everyone says fundraising is a numbers game, so you're building a list of 200 funds.
In short
About 50 funds fit a project closely, and it takes a dozen or so meetings with them before money comes in. Count those meetings, and keep working the same funds for months.
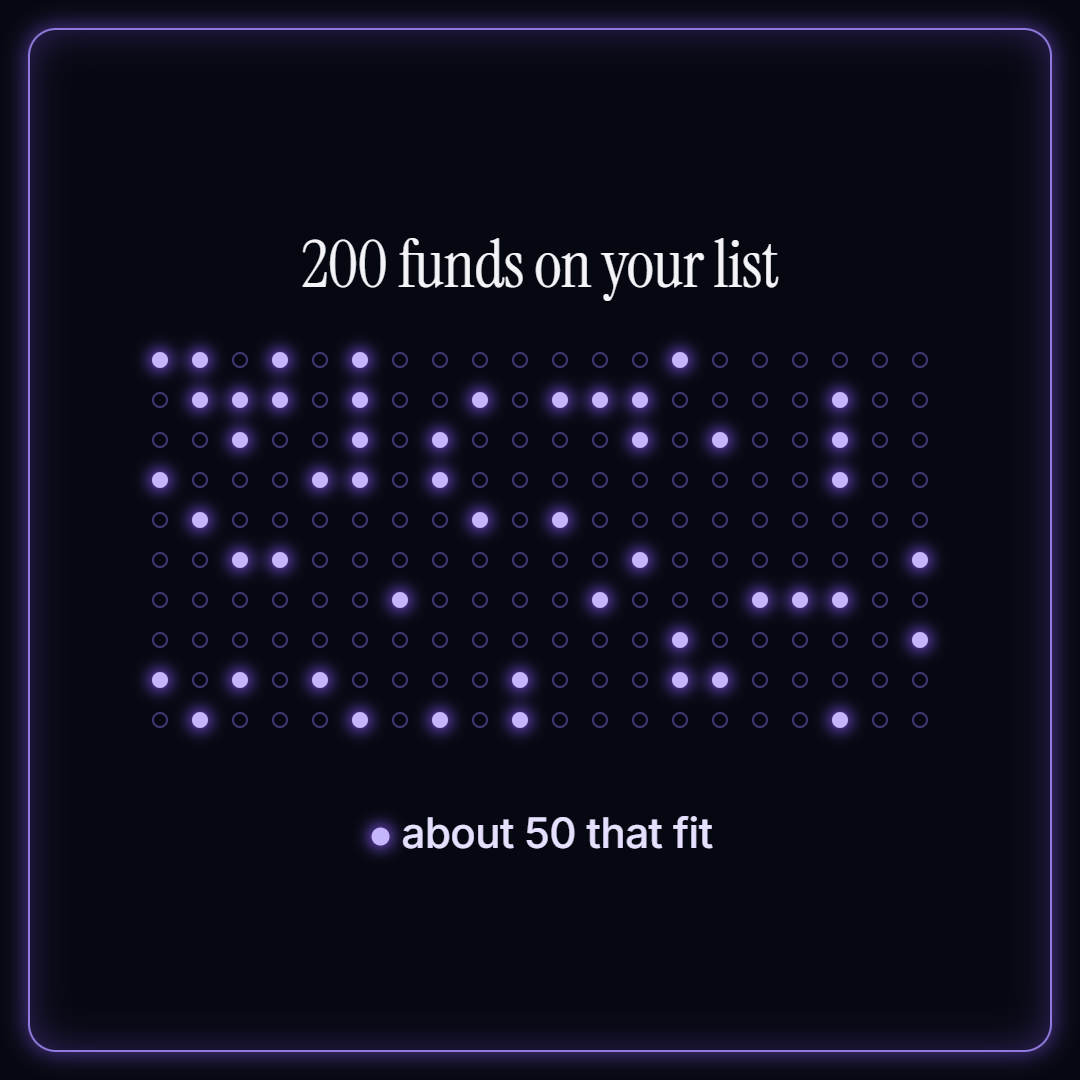
Fundraising is a numbers game, but few founders stop to think which numbers it's about. About 50 funds fit a project closely, and it takes a dozen or so meetings with them before money comes in.
Founders will say "so what if 99% of startups go to zero, i won't be one of them". They believe it, and people praise them for it. Then the same founders look for an equation: this many emails gets this many calls, and this many calls gets the first cheque. They do the maths on the emails, but not on the company.
Is fundraising a numbers game
The number that counts is meetings with funds that fit, whether you sent a million emails or ten.
Some founders think the game is the list: "show me the list, generate me a list, give me a list of the people you know". The list alone doesn't get you a cheque. You can have 10 meetings with funds that fit and 10 cheques, or 100 meetings and none.
Funds play a numbers game of their own. The bigger funds I know get 20 to 40 inbound pitches a day, and that's inbound alone. About 60% of them drop out at automated screening. So imagine what goes on in there.
More calls in your calendar don't create FOMO. You shouldn't tell a fund exactly who else you're talking to until you have a term sheet or a signed SAFE anyway.
It's different when you're raising a bigger round, or you're a super hot project with a really strong round. Then funds fight over it, and it's worth collecting a few offers. But if you're reading this, you probably don't have that. You'd be too busy talking to investors.
How many VCs fit your startup
If I had to give one number, it's about 50 funds that fit a project closely, on average across the teams I talk to.
By that I mean funds that:
- are active, with a deal in the last 12 months
- still have a fund they're deploying from
- have a mandate that fits your geography and your stage
- have someone who invests in roughly what you do and can understand what you're about
And the criteria run both ways, so you fit theirs too.
That's not many. It's closer to a niche with 25 possible customers than to a list of 500.
Think of account-based sales, where only 25 companies fit and the sales cycle takes a year and a half. Some niches are like that, and it doesn't mean the business is bad. They orbit those 25 companies. They meet different people there, run marketing aimed at them, write things those people might care about, content and replies. They watch where those people hang out, online or in person, and they show up there. Think about the funds that fit the same way.
Can AI build your investor list
Research tools are great for this, but you still need to know what case you're making, and to whom.
I've mentioned the tools more than once, a few of them in Nobody will lead your round. A lot of founders work on their project with Claude, then say they want to raise. Claude tells them "great, raise", and "go to these people, they invested in things like this". On that list you get big funds where your odds are lower, generalists, and people who don't invest anymore. Or a fund that looks active because it announced two rounds 10 months ago, though it wrote those cheques a year and a half ago. Announcements run behind, as I wrote in Nobody passed and nobody moved.
Generalist funds can be hard to get through to as well, depending on what you sell. Right now a lot of them like deep tech. If you're in a crowded category instead, there may be 500 other projects writing to them with roughly the same thing, and even if you're objectively better, they won't even see you.
If you're broke and need the money very early, go outside those 50 as well, knowing your odds are lower there: to generalists, to smaller and local programmes, to angels. There's a lot to do there. It's the work nobody wants to sit down and do.
How many investor meetings does it take to raise a seed round
I'd say it takes a dozen or so meetings with funds that fit before money comes in, counting second and third meetings with the same fund.
The smaller pre-seed rounds I've seen happen often went like this. The founder did contact a lot of VCs. But they also went to local events and met other founders, those founders got to know them and sometimes made an intro, and it snowballed. It took much longer than you'd think.
You can track that process the way you'd track emails and replies. You don't need to vibe-code a CRM for it. With about 50 funds that fit, a spreadsheet is enough, and you can write everything down yourself. You do have to be a bit of a stalker.
Why your investor outreach isn't working
Outreach is the tip of the iceberg, and founders skip what's under it.
In sales, outreach is just the tactic, the finish on top. First comes the problem, then the customer, then the customer's profile, then the solution, then how you package it, and only then the outreach.
Raising works the same way. Founders skip the basics: what they're pitching, to whom, how and why. Then they wonder whether to write to 100 funds or 200, when about 50 fit, by email or on WhatsApp, with the deck link right away or not. None of that matters much in the bigger picture. It's just easier to think about.
I've seen a team pitch one kind of fund, and those funds didn't see the point. The team wanted to go towards infrastructure anyway, so they retold the company that way. Suddenly it clicked.
Another team went mostly to local generalist pre-seed funds in Central and Eastern Europe. The local market and culture didn't really back what they were building, so the funds said "cool shit, but i don't really feel it". They went to Western Europe, where their market is more developed and more varied, and the funds there understood it.
What to do when investors don't reply
Keep writing to the funds that fit, without asking for money, and if they don't reply, write again later or somewhere else.
Cold emails are fine as long as there's no ask in them. If they don't reply, you've lost nothing. If they do, check four things: they're the right person for you, you're the right project and founder for them, they're still investing, and the timing is good. If all four hold, talk.
If they don't, write again later when there's something new, or somewhere else, on LinkedIn, by email, on WhatsApp. Meet them at an event, get an intro. You'll orbit around them for half a year, and a fund that didn't reply still hears your wins, as in What to do when a VC says let's talk next round.
In principle, your round is always closed. You're always talking and never raising, unless someone wants to give you money, the rule from Why some rounds never close.